Image on Pinterest
Hurricane season does not care which hospitals are in your insurance network. When an evacuation order forces you out of your home region, a hospital indemnity insurance plan pays a fixed cash benefit directly to you the moment you are admitted to any hospital anywhere in the country, regardless of what your primary health plan pays and regardless of which state you end up in. If you carry a narrow-network or high-deductible health plan and you live within striking distance of a hurricane threat, a hospital indemnity plan may be the most consequential supplemental coverage you do not yet hold.
This guide explains what hospital indemnity insurance is, why a forced evacuation creates specific out-of-network financial risks that your health plan will not fully absorb, where the No Surprises Act falls short in a disaster scenario, and how T-Bridge Finance LLC helps Maryland clients and families across the country close that gap before the next storm arrives.
Related BlogPost
Critical Illness Insurance Claims: The Payout Process in 2026
Hospital Indemnity Insurance 2026: Cruel Gaps Exposed for Families
Mortgage Protection Insurance vs Life Insurance: 2026 Brutal Truth
Mortgage Protection for Hurricane Season: Why August Through October Is the Riskiest Stretch
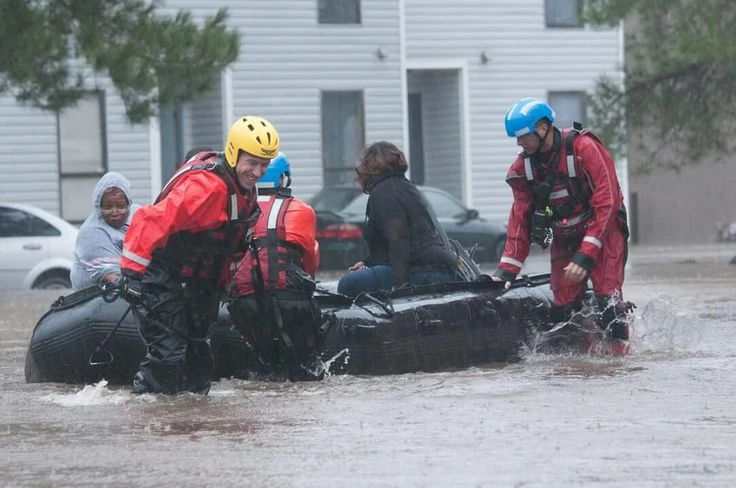
Image on Pinterest
What Is Hospital Indemnity Insurance?
Hospital indemnity insurance is a supplemental insurance policy that pays a predetermined cash benefit directly to the policyholder when they are admitted to a hospital. The benefit is structured as a lump-sum payment on admission, a per-day benefit for each day of confinement, or a combination of both, depending on the plan tier selected.
The payment does not go to the hospital, neither does it route through the primary insurer, it transfers directly to the policyholder, who can apply it toward medical deductibles, ambulance charges, evacuation hotel costs, lost business income, or any other expense created by the hospitalization. There are no restrictions on how the cash is spent, and there are no network requirements that limit which facility triggers the benefit.
Hospital indemnity insurance is not tied to provider networks, so a policyholder can use it no matter where they receive care, and it works alongside many types of health insurance, including employer-sponsored plans, ACA Marketplace coverage, Medicare Advantage, and Medicare Supplement.
According to the Maryland Insurance Administration, hospital indemnity policies typically pay a fixed dollar amount for each day of hospitalization, with the specific benefit amount varying by plan. The MIA also emphasizes that a hospital indemnity plan is a supplemental product and is not a replacement for major medical health insurance. That distinction matters, and any family evaluating this coverage should hold it as a layer on top of, not instead of, comprehensive health coverage.
Why a Hurricane Evacuation Creates an Out-of-Network Medical Emergency
Most Americans with employer-sponsored health insurance carry either a health maintenance organization plan or a narrow-network preferred provider organization plan. Both plan types build their coverage around a defined geographic network of hospitals, physicians, and clinics. Within that network, cost-sharing is predictable and manageable. Outside it, the financial picture changes sharply and quickly.
When a hurricane evacuation order forces a family out of their home region and into a neighboring state, the hospitals available to them in that new location may have no contractual relationship with their home-state insurance plan. Emergency care cannot legally be denied regardless of network status, and that protection matters. What it does not do is override the plan’s own out-of-network cost-sharing schedule.
The KFF 2025 Employer Health Benefits Survey found that the average annual deductible for workers with single coverage and a general annual deductible was $1,886, and 34 percent of covered workers were enrolled in a plan with a deductible of $2,000 or more. An out-of-network hospitalization can trigger that entire deductible in a single admission, and the coinsurance owed after the deductible applies at the out-of-network rate, which is typically 30 to 40 percent, rather than the in-network rate. The average cost of a three-day hospital stay is approximately $30,000, and after an insurer applies its out-of-network payment schedule, the remaining patient liability can reach $8,000 to $12,000 or more on a single admission.
That is not a hypothetical, it is the arithmetic of most mid-tier marketplace and employer plans when applied to an out-of-network emergency, and it arrives in the mail weeks after the storm has passed and the evacuee is already dealing with property damage, business interruption, and the cost of temporary housing.
What the No Surprises Act Does Not Cover During a Hurricane Evacuation
The No Surprises Act, which went into full effect in January 2022, provided meaningful protections against certain categories of surprise medical billing. It prohibited out-of-network physicians and emergency facilities from billing patients beyond their in-network cost-sharing amounts for emergency services. That protection is real, and it eliminated a category of abuse that had financially devastated patients for years.
It did not, however, eliminate the coverage gap that a hurricane evacuation creates.
The No Surprises Act protects patients from balance billing for emergency care, most out-of-network services at in-network facilities, and air ambulance transport, but ground ambulance rides, out-of-network care a patient chooses, and non-emergency care at out-of-network facilities are not covered by the law. Ground ambulance transport is precisely the service most likely to be used during a hurricane evacuation, and it is the one service the No Surprises Act leaves entirely unaddressed at the federal level.
As of 2026, only 22 states have enacted their own ground ambulance balance billing protections for people enrolled in fully insured health plans, and states lack jurisdiction to regulate self-funded employer-sponsored health plans, which cover the majority of American workers. That means a large share of employed Americans have no protection from a ground ambulance balance bill under any current law, federal or state.
The No Surprises Act also does not limit the plan’s own deductible or coinsurance requirements. Even when the hospital itself cannot send a balance bill, the patient still owes whatever their plan’s out-of-network cost-sharing schedule demands. A hospital indemnity plan addresses both of those remaining gaps because its cash benefit pays directly to the policyholder regardless of what any other payer does.
Image on Pinterest
Hospital Indemnity Insurance vs. Standard Health Insurance During an Evacuation
These two products are not alternatives to each other, and understanding the difference between them is essential before hurricane season reaches its peak. A hospital indemnity plan is a supplement to health insurance, not a substitute for it, and each product solves a fundamentally different problem.
What Standard Health Insurance Covers During an Out-of-Network Evacuation Hospitalization
Standard health insurance, including HMO, PPO, and ACA marketplace plans, is required under 45 CFR § 147.138 to cover emergency services regardless of whether the treating facility is inside the plan’s network. The law ensures that coverage cannot be denied on the grounds of network status alone. The coverage applies, the insurer pays its share, and the policyholder pays their share.
The problem lies entirely in that phrase “their share.” An out-of-network emergency admission applies the plan’s out-of-network deductible first, then applies coinsurance at the out-of-network rate after the deductible is satisfied. A plan with a $3,000 out-of-network deductible and 35 percent coinsurance applied to the remaining balance leaves the policyholder owing $3,000 in deductible plus approximately $6,650 in coinsurance on a $22,000 billed admission, for a total net exposure of nearly $9,650.
The plan covers the rest, but that rest comes only after the patient has fully funded the deductible and the coinsurance out of their own pocket, at a moment when their household budget is simultaneously absorbing evacuation expenses, hotel costs, and potentially lost business income.
What Hospital Indemnity Insurance Covers During an Out-of-Network Evacuation Hospitalization
A hospital indemnity insurance plan bypasses the primary plan’s deductible and coinsurance structure entirely. The benefit triggers upon a covered hospital admission, the cash transfers directly to the policyholder, and the policyholder applies it however the situation demands. Hospital indemnity policies pay out when the insured is admitted to any hospital and do not restrict care to a certain network, which is the defining difference from PPOs and HMOs, and the payment goes directly to the insured rather than to the hospital.
That unrestricted, network-agnostic cash payment is what makes a hospital indemnity plan the most practically useful supplemental tool in an evacuation scenario. The policyholder does not need to navigate claim routing between two insurers. They do not need to wait for the primary insurer to settle first, they file one claim with the hospital indemnity carrier, confirm the admission, and receive a direct deposit or check that they can apply to the deductible, the ambulance bill, the hotel, or the credit card balance that funded the evacuation.
What T-Bridge Finance LLC Consistently Sees Among Maryland Clients
Beyond the numbers, what the team at T-Bridge Finance LLC consistently observes among small business owners, diaspora investors, and high-income professionals in the Maryland market is a specific pattern of coverage blind spots. These clients typically carry strong primary health insurance, and they have invested carefully in life insurance and estate planning. What they have almost never done is evaluate whether their primary health plan would perform adequately outside their immediate geographic region when they had no choice of facility and no time to make one.
The assumption that “emergency care is covered everywhere” is partially true and fully dangerous at the same time. Emergency care is covered, but the patient’s share of the bill in an out-of-network setting can still be financially devastating, particularly for a small business owner who is simultaneously dealing with storm damage to their property, a disrupted revenue stream, and the day-to-day costs of displacement.
Dr. Taiwo Akindahunsi and the T-Bridge Finance LLC team address this gap directly during the firm’s Insurance Planning review process. The approach is to calculate the client’s actual worst-case out-of-network exposure from their existing primary health plan before recommending any supplemental product. That calculation takes one conversation and produces a specific dollar figure that tells the client exactly how much cash benefit they need from a hospital indemnity plan and at what monthly premium they can obtain it.
Who Should Consider Hospital Indemnity Insurance Before Hurricane Season?
People between the ages of 65 and 84 make up approximately one in three hospital visits according to the Agency for Healthcare Research and Quality, and the cost of an average stay is nearly $14,000, which Medicare plans rarely cover in full. Medicare Advantage plans carry an annual out-of-pocket maximum that can reach $6,700 or more, which exceeds the emergency savings available to most American households. Hospital indemnity insurance is a recognized tool for closing that gap at any age.
For people under 65, the highest-risk profiles share three characteristics. The first is enrollment in a narrow-network or HMO plan, which offers the most geographically restricted coverage. The second is carrying a high deductible that has not been fully offset by an HSA balance. The third is self-employment or ownership of a small business, where a hospitalization simultaneously eliminates income and triggers a significant out-of-pocket obligation.
Marketplace plan enrollees in coastal states face compounded risk because individual plan premium increases in Maryland for 2026 range from 8.1 to 18.7 percent, which has pushed many Marylanders toward plans with higher deductibles in order to manage monthly premium costs. A higher deductible means greater exposure at exactly the moment a hurricane forces them to an out-of-network facility.
Families with employer-sponsored self-funded plans face their own version of this risk because, as noted above, those plans are not subject to state-level ground ambulance balance billing protections regardless of which state the employer is based in.
How to Get Hospital Indemnity Insurance Before the Next Storm
Obtaining a hospital indemnity plan does not require replacing or cancelling any existing coverage. It is a supplemental product that adds a cash benefit layer on top of whatever primary health, Medicare, or employer plan a person already holds. There is no network approval process and no claim routing requirement through the primary insurer.
Most hospital indemnity policies include coverage for hospital stays, ICU stays, and critical care units, with no deductibles or network restrictions, and because benefits are paid directly to the insured, the policy can often remain in force even when the insured changes jobs.
The most effective approach before hurricane season is a structured review with a licensed financial advisor who can examine the specific out-of-network exposure created by the primary health plan, calculate the dollar gap between coverage and liability, and match a hospital indemnity plan tier to that gap at a premium that fits the household budget. Dr. Taiwo Akindahunsi and the T-Bridge Finance LLC team provide exactly that review as part of the firm’s broader Insurance Planning service, serving clients across Maryland and the Mid-Atlantic region with particular depth in Anne Arundel County.
Schedule a Consultation Before Hurricane Season Closes
The Atlantic hurricane season runs through November 30. Every week that passes without a hospital indemnity plan in place is a week of unhedged financial exposure for any family that could be forced out of their insurance network by a storm. Reach out to Dr. Taiwo Akindahunsi and the team at T-Bridge Finance LLC to schedule a no-obligation Insurance Planning review.
The review examines your existing health plan’s out-of-network cost-sharing schedule, calculates your realistic worst-case liability in an evacuation hospitalization, and identifies the hospital indemnity plan tier that closes that gap at a monthly premium that fits your budget. Schedule your consultation today.
About the Author
Maxwell is a financial content strategist at T-Bridge Finance LLC, a financial services firm based in Bowie, Maryland. All articles published on this blog are reviewed by the licensed PROFESSIONALS at T-Bridge Finance LLC before publication to ensure accuracy and compliance with current insurance and financial guidelines. T-Bridge Finance LLC holds active insurance licenses and serves families across the United States with life insurance, estate planning, college funding, and tax-advantaged wealth strategies. schedule a free consultation.
FAQ
1. What is hospital indemnity insurance?
Hospital indemnity insurance is a supplemental policy that pays a fixed cash benefit directly to the policyholder upon a covered hospital admission. The benefit is typically structured as a per-admission lump sum, a per-day confinement benefit, or both. The payment goes to the insured person and can be applied toward medical bills, deductibles, ambulance charges, or any non-medical expense resulting from the hospitalization. Hospital indemnity insurance is not major medical coverage and does not satisfy ACA minimum essential coverage requirements under federal law.
2. Does hospital indemnity insurance pay if I am hospitalized out of state during a hurricane evacuation?
Yes. A hospital indemnity plan pays its benefit regardless of which state or which hospital the policyholder is admitted to. Because hospital indemnity insurance carries no network restrictions, the cash benefit applies whether the facility is in-network, out-of-network, or located in a completely different region of the country. This network independence is the primary reason hospital indemnity insurance is valuable during a forced evacuation.
3. Does the No Surprises Act protect me from all out-of-network bills during an evacuation?
No. The No Surprises Act prohibits out-of-network physicians and emergency facilities from balance billing patients above the in-network cost-sharing amount, but it does not eliminate the primary health plan’s own deductible or coinsurance requirements. Ground ambulance services are explicitly excluded from the law’s protections. As of 2026, lawmakers in at least two additional states are considering ground ambulance legislation, but federal action has stalled, leaving the majority of Americans without comprehensive protection from ground ambulance balance bills. A hospital indemnity plan’s unrestricted cash benefit covers both the plan’s cost-sharing charges and any ambulance balance bill.
4. How much does hospital indemnity insurance cost per month?
Monthly premiums for hospital indemnity plans range from as low as $7 per month for minimal coverage to approximately $463 per month for comprehensive plans, with costs varying based on age, location, gender, and the carrier selected. Most individual policyholders in the working-age range who need sufficient daily benefit coverage to offset a standard high-deductible will find adequate plans in the $50 to $150 per month range. T-Bridge Finance LLC’s Insurance Planning review process identifies the benefit level needed to close a specific client’s exposure gap and matches it to the appropriate premium tier.
5. What is the difference between hospital indemnity insurance and critical illness insurance?
Hospital indemnity insurance pays a cash benefit whenever the insured is admitted to a hospital for any covered reason, including fractures, infections, and surgical procedures that may result from an evacuation. Critical illness insurance pays a separate lump-sum benefit only when the insured is diagnosed with a specific qualifying condition such as a heart attack, stroke, or cancer diagnosis. Both products pay cash directly to the policyholder with no network restrictions, and both can be held simultaneously. An evacuation-related injury or acute illness would typically trigger the hospital indemnity benefit but would not trigger a critical illness benefit unless the diagnosis qualifies under the critical illness plan’s specific terms.
Disclaimer: The information in this article is for educational purposes only and does not constitute financial, legal, or insurance advice. Life insurance and financial products vary by carrier, state of residence, age, health profile, and individual circumstances. Past index performance does not guarantee future results. Cash value illustrations referenced in this article are hypothetical projections and not a guarantee of policy performance. T-Bridge Finance LLC is a licensed financial services firm operating in the United States. Please consult a licensed financial advisor or insurance professional before making any insurance or financial planning decisions. To speak with our team, contact us here.